Dollar Tree 401k Plan: Enrollment Benefits, Withdrawals and Login Guide (2026)
Introduction to Dollar Tree 401(k) Plan
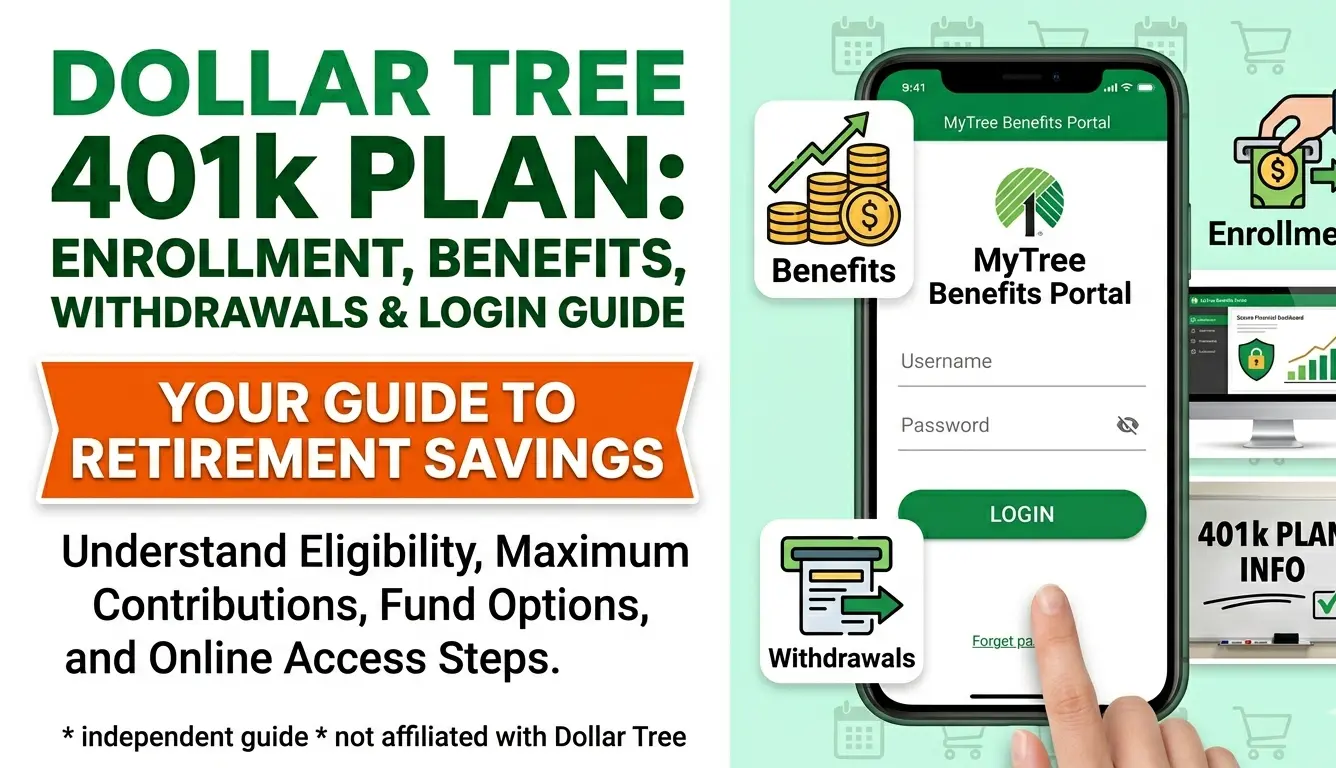
The Dollar Tree 401(k) Plan is one of the most important employee benefits for long-term savings in the United States. It is officially known as the Dollar Tree Retirement Savings Plan. This plan is managed by Empower Retirement, a trusted retirement service provider.
It helps employees save money from their paycheck and build a strong retirement fund over time. Workers can also get employer matching, which adds extra money to their savings. This makes the plan very useful for building financial security for the future.
Employees can check their account anytime using the online portal at dollartree.com/retire or through the Empower Retirement app. The plan is designed to make saving simple, flexible, and tax-friendly.
What is a 401(k) Plan and How It Works
A 401(k) plan is a retirement savings account offered by employers. It allows workers to save part of their income before taxes are taken out. This means you pay less tax today while saving more for the future.
Over time, your money grows through investments and compound interest. This helps your savings increase faster without extra effort. Many employees use this plan because it is one of the easiest ways to prepare for retirement.
The Dollar Tree 401(k) follows this same structure but also includes employer contributions, investment choices, and online account access.
Key Features of the Dollar Tree 401(k) Plan
Plan Overview
The Dollar Tree 401(k) plan comes with simple and flexible features that help employees save money easily.
- Plan Provider: Empower Retirement
- Eligibility: Age 21+, 1 year of service, 1,000 hours worked
- Investment Options: Mutual funds, target-date funds, bond funds
- Loan Option: Available under plan rules
- Hardship Withdrawal: Allowed in special cases
Employer Match Benefits
Dollar Tree also adds extra money to your savings.
- Match Rate: 50% of the first 6% you contribute
- Example: If you contribute 6%, company adds 3%
- Vesting: Full ownership after 5 years
This means the company helps you grow your retirement savings faster.
Dollar Tree 401(k) Enrollment Guide
How to Join the Plan
Joining the plan is simple once you become eligible.
- Visit dollartree.com/retire
- Click on “Register”
- Enter your personal details (SSN, DOB, ZIP code)
- Create your login account
- Choose your contribution rate
- Select your investment options
Once completed, your deductions start automatically from your paycheck.
When You Can Enroll
Employees can join after:
- 1 year of service
- 1,000 working hours completed
- Meeting age requirement (21+)
You can also change your contribution anytime through the portal.
Dollar Tree 401(k) Login and Access Guide
How to Log In Online
You can access your account easily without any app.
- Go to dollartree.com/retire
- Click “Access My Account”
- Enter username and password
- Check balance, contributions, and statements
Using the Mobile App
You can also use the Empower Retirement app:
- View account balance
- Change contribution rate
- Track investment growth
Login Troubleshooting Tips
If you cannot log in:
- Check username and password
- Reset your password if needed
- Make sure internet connection is stable
- Contact Empower support if required
This ensures smooth access to your retirement account anytime.
Dollar Tree 401(k) Employer Match Explained
How the Company Match Works
The Dollar Tree 401(k) plan includes a helpful employer match that increases your retirement savings. This means the company adds extra money based on what you contribute.
When you save from your paycheck, the company rewards you with additional funds. This is one of the best benefits of working at Dollar Tree.
Simple Match Example
- You contribute 6% of your pay
- Dollar Tree adds 50% of that amount
- That means an extra 3% goes into your account
This is free money added to your retirement savings, helping your balance grow faster over time.
Vesting Rules
Employer contributions do not fully belong to you right away. You must stay with the company for a certain time.
- Full vesting after 5 years
- Before that, you own a portion based on years worked
This encourages long-term savings and job stability.
Dollar Tree 401(k) Contribution Limits (2025)
Employee Contribution Limits
The IRS sets yearly limits on how much you can save in your 401(k).
- Under 50 years old: $22,500 per year
- 50 years or older: $30,000 per year (includes catch-up contribution)
You can choose how much to contribute from each paycheck, such as 3%, 6%, or more.
Easy Contribution Control
You can change your contribution anytime through the online portal. This helps you adjust savings based on your budget and goals.
Investment Options in Dollar Tree 401(k)
Where Your Money Goes
Your contributions are not just saved in cash. They are invested in different funds to help your money grow.
The plan managed by Empower Retirement offers several choices:
Target-Date Funds
These automatically adjust as you get closer to retirement. They become safer over time.
Mutual Funds
These include stocks and bonds managed by professionals. They aim for long-term growth.
Bond Funds
These are lower-risk investments. They focus more on safety and stable returns.
Choosing the Right Mix
You can choose aggressive, balanced, or conservative options based on your risk level. You can also change investments anytime.
Managing Your Dollar Tree 401(k) Account
Easy Account Control
You can manage everything online or through mobile access.
- Check balance anytime
- Change contribution rate
- Update investment choices
- Add or change beneficiaries
Why Account Management Matters
Regular account checks help you:
- Track your retirement growth
- Adjust savings when income changes
- Keep your investment plan updated
Managing your account often can improve long-term results.
Dollar Tree 401(k) Withdrawals and Rules
When You Can Withdraw
You may take money out in special situations such as:
- Retirement age
- Financial hardship
- Leaving the company
Early Withdrawal Rules
If you withdraw before age 59½:
- 10% IRS penalty may apply
- Income tax will be deducted
- Your retirement savings will decrease
Hardship Withdrawals
Some emergency situations may allow early access, such as:
- Medical emergencies
- Home purchase needs
- Major financial hardship
But withdrawals should be a last option.
What Happens When You Leave Dollar Tree
Options After Leaving Job
When you leave Dollar Tree, you have several choices:
- Keep money in the plan
- Roll over to an IRA
- Move to a new employer’s 401(k)
- Cash out (not recommended)
Rollover Benefits
A rollover keeps your money growing without penalties. It is usually the safest option for long-term savings.
How to Withdraw Money from Dollar Tree 401(k)
Withdrawal Basics
Withdrawing money from your 401(k) plan should be done carefully. This account is made for retirement, so early use can reduce your future savings.
In the plan managed by Empower Retirement, you can request withdrawals based on rules set by the IRS and your employer.
Types of Withdrawals
You may see different withdrawal options:
1. Full Withdrawal
You take all your money out of the account. This is usually done after leaving the company or retiring.
2. Partial Withdrawal
You take only a part of your savings while keeping the rest invested.
3. Hardship Withdrawal
This is allowed in emergencies such as:
- Medical bills
- Housing needs
- Serious financial problems
Early Withdrawal Penalty
If you withdraw before age 59½:
- 10% penalty may apply
- Income tax will be deducted
- Your long-term savings will shrink
So, it is better to avoid early withdrawal if possible.
Rollover Options for Dollar Tree 401(k)
What is a Rollover?
A rollover means moving your retirement money to another account without losing tax benefits. This is a smart option after leaving Dollar Tree.
Main Rollover Choices
1. Rollover to IRA
You move your money into an Individual Retirement Account. Benefits include:
- More control over investments
- More investment options
- Long-term growth flexibility
2. New Employer 401(k)
If your new job offers a 401(k), you can transfer your old balance there.
3. Keep in Current Plan
You can leave your money with Empower Retirement, but you cannot add new contributions.
4. Cash Out (Not Recommended)
You get money immediately, but:
- Taxes apply
- Penalties reduce your balance
- You lose future growth
Best Choice
Most financial experts recommend an IRA rollover for better control and lower risk of penalties.
After Termination Rules
What Happens After You Leave Job
When you leave Dollar Tree, your 401(k) account does not disappear. It stays active under your name.
Small Account Rule
- If balance is under $1,000: it may be cashed out automatically
- If balance is higher: you can keep or transfer it
Important Decision
You should decide quickly what to do with your account to avoid unwanted tax issues.
How to Fix Login Problems
Common Login Issues
Sometimes employees face problems accessing their account at dollartree.com/retire.
Common reasons include:
- Wrong password
- Forgotten username
- Account locked
- Browser issues
Simple Fix Steps
Reset Password
Click “Forgot Password” and follow instructions.
Clear Browser
Clear cache and cookies if website is not loading.
Use Correct Portal
Always use official login page:
- dollartree.com/retire
- familydollar.com/retire
Contact Support
If nothing works, contact Empower support for help.
Empower Retirement Contact Information
Customer Support
If you need help with your 401(k), you can contact support easily.
- Phone: 1-855-756-4738
- Hours: Monday to Friday, 8 AM – 10 PM ET
- Website: empower.com
You can also contact HR at Dollar Tree for payroll or eligibility questions.
Tips to Maximize Your 401(k) Savings
Simple Saving Tips
To get the most from your retirement plan:
- Always contribute enough to get full employer match
- Increase contribution every year
- Avoid early withdrawals
- Choose balanced investment options
- Check your account regularly
Why It Matters
Small contributions today can grow into large savings in the future due to compound interest.
Conclusion
The Dollar Tree 401(k) Plan is a strong retirement benefit that helps employees save money for the future with ease. It offers tax savings, employer matching, and flexible investment options. With support from Empower Retirement, employees can manage their accounts online, track growth, and plan for retirement with confidence. Whether you are just starting a job or planning to leave, understanding your 401(k) options helps you make smarter financial decisions. Keeping your money invested for the long term is the best way to build a secure and stable retirement future.
Watson Shon
Hi, I’m Watson Shon. I am a former Regional HR Manager at Dollar Tree. I also have a Bachelor’s degree in Human Resource Management from Old Dominion University. I have real experience helping employees use Dollar Tree systems and understand their work tools.
I created Dollar-TreeCompass.com as an independent guide. My goal is to make things simple and easy for employees. This site shares clear steps based on real workplace experience, not guesswork.